News & Media
Featured
Harmony’s US$1.08 billion MAC Copper deal effective 24 October
Tuesday, October 14, 2025
What's in this article
So, in a nutshell
Acquisition size & premium: Harmony is acquiring MAC Copper for US$12.25 per share in cash, implying a US$1.03 billion equity valuation and offering ~20.7% premium to its last closing price
Strong operating asset: CSA is a high-grade underground copper mine, producing ~41 kt in 2024, with favorable cost metrics and margin potential.
Long life and exploration upside: The mine has a reserve life of over 12 years and development upside via the Merrin Mine and zinc discoveries
Financing approach: The deal is backed by a US$1.25 billion bridge facility plus Harmony’s strong cash reserves; post-deal leverage is expected to stay conservative
Regulatory and structural complexity: The scheme requires multi-jurisdictional approvals, robust shareholder support, and the assumption of streaming and royalty contracts, making execution a key hurdle MAC’s sole asset is the CSA Copper Mine, an underground operation located about 700 km west-northwest of Sydney in New South Wales’ Cobar region. In calendar year 2024, CSA produced about 41,000 tonnes (≈ 41 kt) of copper, making it one of Australia’s higher-grade copper producers
Strategic rationale and corporate fit
Harmony describes the acquisition as a transformational step in diversifying beyond gold into copper, thereby lowering exposure to gold price volatility and strengthening its global footprint. The CSA asset fits Harmony’s investment criteria, emphasizing free cash flow generation, operational quality, and margin resilience. CEO Beyers Nel emphasised that Harmony will leverage its underground mining experience to further optimise CSA.
The deal complements Harmony’s existing Australasia presence (including the Eva Copper Project in Queensland) and supports its goal of becoming a low-cost, globally diversified gold and copper producer. Harmony cites a track record of successful acquisitions, Hidden Valley (PNG, 2016), Moab Khotsong (2018), Mponeng, Mine Waste Solutions (2020) and Eva Copper (2022) as evidence of its integration capability.
Key highlights of the transaction
Operational metrics: In 2024, CSA’s C1 cash cost (after by-product credits) was US$1.92/lb and its all-in sustaining cost (post credits) was US$2.92/lb. This enabled an estimated free cash flow margin of ~36%
Reserve life and upside: CSA has a current life of more than 12 years, stable resource replacement, and additional exploration upside. Among the developments is the Merrin Mine (located in upper parts of CSA), with first ore expected in December 2025, and newly announced zinc mineralisation
Financing & balance sheet: The acquisition will be funded via a US$1.25 billion bridge facility plus Harmony’s existing cash reserves. Harmony already held net cash of ~R10,831 million (US$592 million) at 31 March 2025. Post-deal, net debt/EBITDA is expected to remain comfortably below 1.0×
Streams and royalties: Harmony will assume MAC’s existing silver and copper streaming contracts with Osisko, and a 1.5% net smelter return royalty to Glencore. Additional contingent payments to Glencore are triggered if copper prices exceed certain thresholds over sustained periods
Implementation and approvals: The transaction is structured via a Jersey law scheme of arrangement. It requires court sanction (to be lodged with the Jersey Registrar), MAC shareholder approval (at least 75% by vote), and regulatory approvals (including from South African Reserve Bank, Australian FIRB, ASIC, and ASX).
Outlook and points to consider
The acquisition could reposition Harmony as a stronger mid-tier producer with balanced exposure to both precious and base metals. The CSA asset provides near-term cash flows, long life, and further upside from deeper, higher-grade zones and zinc optionality.
However, risks remain. The transaction hinges on multi-jurisdictional regulatory approvals and successful integration of streaming and royalty obligations. Commodity cycles, cost inflation, and execution on the Merrin development and exploration program add further uncertainty.
Overall, the deal underscores the industry trend of gold miners diversifying into copper to capture exposure to electrification and energy transition metals. For Harmony, it’s a strategic step toward becoming a more robust, diversified mining company - if it can navigate the complexities ahead.
RELATED: Export curbs loom as South Africa targets illegal chrome mining
Market News
Related articles
Articles
Thursday, October 15, 2026
Fortescue’s Bélinga project tops $600 m in spending as Gabon iron-ore ambitions advance
Fortescue has significantly increased its investment and exploration activity at Gabon’s Bélinga iron-ore project.
Articles
Wednesday, October 14, 2026
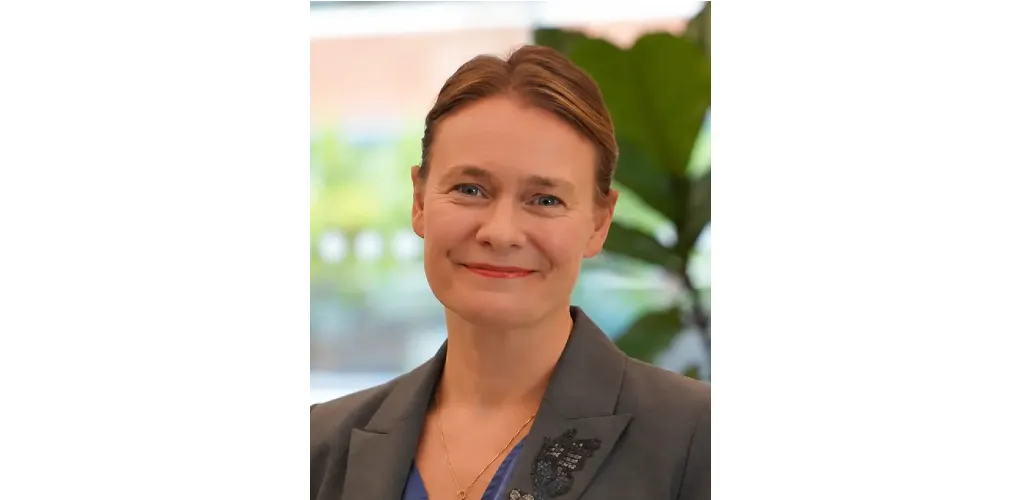
A new chapter for ICMM as Froydis Cameron-Johansson takes the helm
The mining and sustainability leader will take over as President and CEO of the ICMM on 23 November, succeeding Rohitesh Dhawan after more than five years at the helm.
Articles
Thursday, October 8, 2026
Mintek SCi 2026 puts emerging researchers at the forefront of Africa’s future
More than 300 emerging researchers, students, academics and industry stakeholders participated in Mintek SCi 2026, a weeklong innovation programme.